Car insurance: 2 important things most people don’t know
1. If you don’t plan on making a claim… raise your deductible.
When you insure your car, one of the things that directly affects your premium is the amount of your deductible (the part you pay yourself when you make a claim).
If you’re the careful type, you don’t drive much, or you’d rather pay for small damage yourself, raising your deductible can save you 5% to 15% on your monthly premium.
Put simply: you take on a bit more risk, but you pay less every month.
👉 Example: going from a $500 deductible to $1,000 can lower your premium, depending on your insurer. But before you do it, just make sure you’d be comfortable paying that amount if an accident happened.
2. Claim or not? Do the real math before you decide
A lot of drivers think:
“If I claim, my premium is going to explode” or “I’ll pay for it myself, it’ll cost me less.”
But the reality is usually more nuanced.
In a lot of cases, a claim costs less than you’d think
Here’s a concrete example:
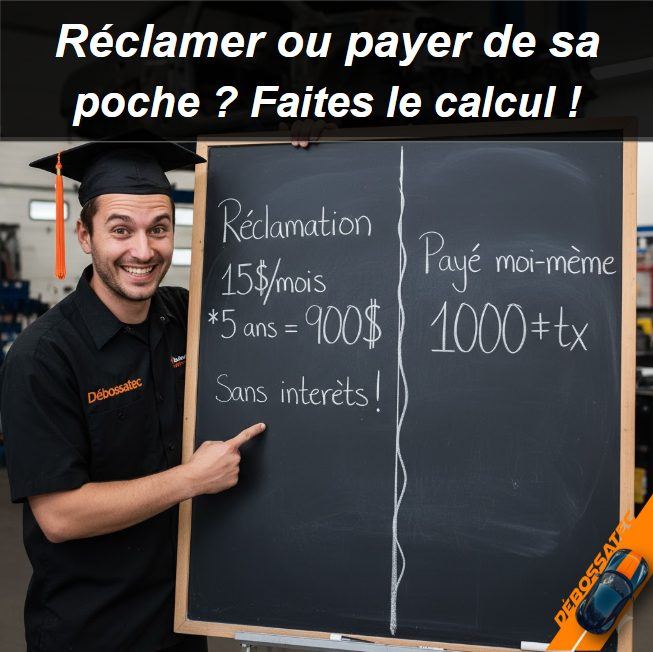
- You have a cracked windshield that costs about $1,000 to replace.
- If you fix it through your insurance, your premium could go up by about $10 to $15 a month (in some cases, not at all if it’s no-fault “glass breakage” coverage).
- That works out to about $180 a year, or $900 over 5 years.
💡 In other words, your windshield ends up costing you like a 5-year payment plan, interest free. And if it’s your first claim or no-fault damage, your premium might not move at all.
3. Before you decide, get the facts
Few people know they have the right to call their insurer and ask the question before filing an official claim. Just ask:
“If I claim for this damage, what would the impact be on my premium?”
The insurer can run a simulation without opening an official file. It’s free, and it lets you decide with your eyes open.
4. And after that?
A claim generally stays on your record for 3 to 6 years, depending on the company. But if you go several years without a claim, your premium comes back down gradually. Some insurers even offer “accident forgiveness” on a first claim.
In short
✔️ Raising your deductible if you don’t plan to claim can lower your premium.
✔️ A lot of claims (glass breakage, no-fault, etc.) have no major impact on your premium.
✔️ Before you decide, call your insurer to find out the real consequences.
✔️ After a few years with no claims, your premium comes back down.
📍 Got a dent, a fender bender or need a paint touch-up?
Drop by any time, no appointment needed.
208 Rue Kennedy, Terrebonne, Qc